The concept of the investor awareness program refers to educating people about investments, financial risk analysis, fraud detection, and money-making. The phrase is associated with several investment-related initiatives, particularly in the US, where it does not refer to any one single standardized government plan.
A useful investor awareness program should go beyond explaining stocks and mutual funds. It should teach people how risk works, why diversification matters, how fees affect returns, how to research investment professionals, and how to identify potentially fraudulent opportunities.
This guide explains what investor awareness means, the seven practical rules investors should know, whether doubling money in five years is realistic, and how US investors can make better-informed decisions.
What Is an Investor Awareness Program?
An investor awareness program is an educational initiative that helps people understand investments, financial risks, investment products, fraud prevention, and responsible investment decisions. Its goal is to enhance financial literacy, not guarantee profits from investments.
A good program may cover:
- Basic investing terminology
- Stocks, bonds, mutual funds, ETFs, and other investments
- Risk and return
- Asset allocation and diversification
- Investment fees and expenses
- Long-term financial planning
- Retirement investing
- Investment fraud and scam prevention
- How to research financial professionals
- Investor rights and responsibilities
The US Securities and Exchange Commission (SEC), through Investor.gov, provides educational resources covering investing basics, compound growth, risk, asset allocation, diversification, investment products, and fraud prevention. That distinction matters. Investment awareness is about improving your ability to make decisions; it is not a promise that an investment will make money.
How Investor Awareness Works
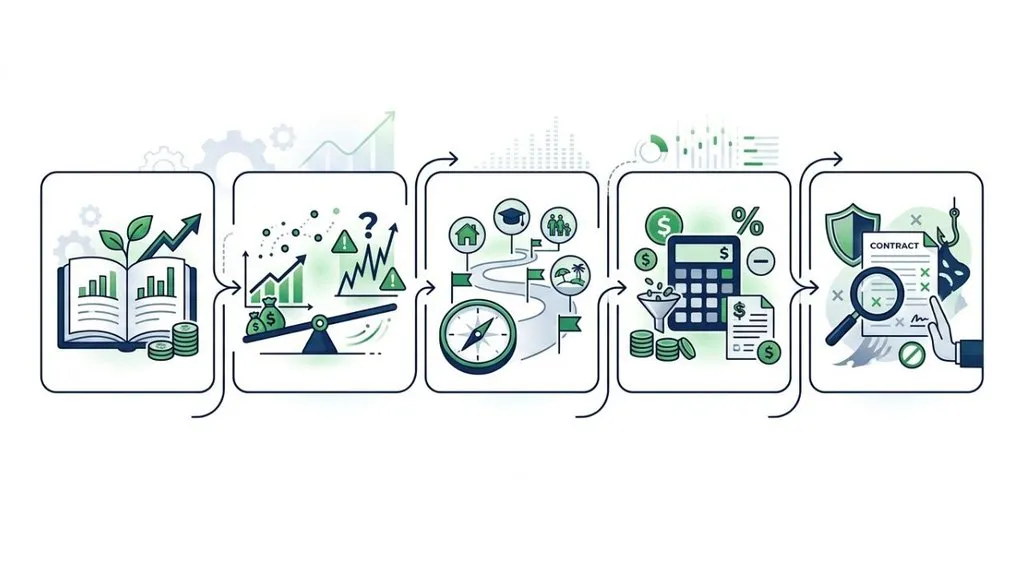
An effective investor awareness program usually follows a simple progression.
1. Learn the basics
Investors first learn the difference between saving and investing, how common investment products work, and what terms such as volatility, liquidity, diversification, and risk tolerance mean.
2. Understand risk
Every investment involves some level of risk. The SEC explains that investment risk refers to uncertainty and the potential for financial loss. Generally, investments offering greater potential returns also involve greater risk.
3. Match investments to goals
A person saving for a short-term goal may have different needs from someone investing for retirement decades away. Time horizon, financial goals, and ability to tolerate losses all influence an appropriate investment approach.
4. Evaluate costs and products
Investors should understand what they are buying and what they are paying. Investment products can incur fees and expenses that reduce the amount of money ultimately remaining in an investor’s portfolio.
5. Learn fraud prevention
Awareness also means knowing when an opportunity deserves skepticism. Promises of unusually high returns with little or no risk, pressure to act immediately, and claims of guaranteed investment profits are important warning signs.
Why Investment Awareness Matters
Awareness of investment enables individuals to make decisions based on intentions, risks, costs, and reliable information rather than on emotion or hype. Improved financial literacy allows investors to identify frauds and errors that can affect their finances for a long time.
Consider an investor who sees a social-media post promising extraordinary returns from a little-known cryptocurrency or stock. Without basic financial knowledge, the opportunity may appear attractive.
An informed investor is more likely to ask:
- What exactly am I buying?
- How does the investment generate returns?
- What could cause me to lose money?
- What fees apply?
- Can I sell when I need the money?
- Who is offering or recommending it?
- Is the investment professional properly registered?
- Are the claimed returns realistic?
This questioning mindset is one of the most valuable outcomes of investor education.
Diversification is another key lesson. Investor.gov explains that spreading money across different investments can reduce the impact of a single investment underperforming. However, diversification cannot eliminate losses when markets fall broadly.
What Are the 7 Rules of Investing?
There is no single official US list called the “7 rules of investing.” However, seven practical principles are widely useful: define goals, understand risk, diversify, control costs, invest according to your time horizon, avoid emotional decisions, and research before investing.
1. Start with a goal
Know why you are investing. Retirement, education, a home purchase, and long-term wealth building can require different strategies.
2. Understand your risk
Do not buy an investment simply because someone says it has high potential. Ask how much you could lose and whether you could financially handle that loss.
3. Diversify
Spreading investments across assets and securities can reduce concentration risk. Diversification does not guarantee profits or prevent losses.
4. Pay attention to costs
Fees may appear small, but recurring expenses can affect portfolio growth over many years. Always understand the costs associated with buying, owning, and selling an investment.
5. Match investments to your time horizon
Money needed soon generally calls for a different level of risk than money intended for a retirement goal many years away.
6. Control your emotions
Fear and greed can encourage investors to buy on excitement or sell in a panic. A written investment plan can make it easier to stay disciplined.
7. Research before investing
Understand the investment and the person or firm offering it. For US investors, FINRA’s free BrokerCheck tool can help research registered investment professionals and brokerage firms.
Can I Double My Money in 5 Years?
Yes, it is mathematically possible, but it is not guaranteed. To double an investment in exactly five years through compounding, you would need an annualized return of approximately 14.87%, before considering taxes, fees, and other costs.
For example, $10,000 growing at 14.87% annually would be approximately $20,000 after five years if that return were achieved consistently.
The important point is that 14.87% is a mathematical requirement, not a promised investment return.
Anyone offering a five-year doubling strategy should be particularly wary of investors. The SEC cautions that promises of high returns with little or no risk are a red flag of possible investment fraud.
A realistic financial plan should focus on goals, diversification, risk tolerance, costs, and time horizon rather than starting with a target return that an investment must deliver.
Common Investments Covered by Investor Awareness
Investor education can introduce people to many types of financial products, but understanding a product does not mean it is suitable for every investor.
| Investment | Basic idea | Important consideration |
| Stocks | Ownership in a company | Market and company-specific risk |
| Bonds | Lending money to an issuer | Interest-rate and credit risk |
| Mutual funds | Pooled investments managed according to a strategy | Fees, strategy, and underlying holdings |
| ETFs | Funds traded on an exchange | Market risk, costs, and underlying assets |
| Treasury securities | Debt issued by the U.S. government | Maturity and interest-rate considerations |
| Crypto assets | Digital assets using blockchain technology | High volatility and significant risk |
Investor.gov lists stocks, bonds, mutual funds, ETFs, annuities, alternative investments, and crypto assets among investment products investors may encounter. It also emphasizes the need to consider risk, fees, diversification, liquidity, and fraud.
It is also important for investors to know the difference between bank deposits and investments. FDIC deposit insurance protects qualifying deposit accounts at FDIC-insured banks, but stocks, bonds, mutual funds, crypto assets, and some other non-deposit products are not FDIC-insured.
How to Evaluate an Investor Awareness Program
Not every financial education session provides the same value. Before relying on a program, look for several characteristics.
Educational rather than promotional
A strong program should explain both potential benefits and risks. Be cautious if education quickly turns into pressure to purchase a particular product.
Clear explanations
Financial concepts should be explained in understandable language rather than buried beneath complicated terminology.
Reliable sources
Look for information supported by regulators, government agencies, recognized financial organizations, or clearly identified primary sources.
Practical fraud education
A useful program should explain how scams work and what investors can do before sending money.
No guaranteed-return claims
Education should never imply that learning about investing eliminates investment risk.
For a US investor considering professional assistance, checking registration and disciplinary information can be an important part of due diligence. FINRA’s BrokerCheck provides background information on investment professionals and brokerage firms registered with FINRA or a national securities exchange.
Common Investor Awareness Mistakes to Avoid
Even investors who understand the basics can make avoidable mistakes.
- Chasing guaranteed returns: No legitimate investment can remove all investment risk simply by promising a high return.
- Ignoring fees: Costs can reduce long-term results.
- Putting too much money into one investment: Concentration can increase portfolio risk.
- Investing without an emergency cushion: Money needed for immediate expenses should not automatically be exposed to market volatility.
- Following social-media hype: Popularity does not prove that an investment is appropriate.
- Failing to research a professional: Check credentials and registration before relying on financial advice.
- Confusing education with advice: An awareness program can provide general financial education but may not determine what is appropriate for your personal situation.
- Assuming past performance will continue: Historical results cannot guarantee future results.
Proper research is an important part of investor due diligence and can help you identify potential red flags before committing your money.
Frequently Asked Questions
What is investment awareness?
Investment awareness means understanding how investments work, including their potential returns, risks, costs, liquidity, and suitability for different financial goals.
It also includes recognizing scams and making decisions based on reliable information.
What is an investor awareness program?
It is an educational program designed to help people understand investing, financial risks, investment products, fraud prevention, and responsible financial decision-making.
In the US, investor education is provided through resources such as Investor.gov.
What are the 7 rules of investing?
A practical seven-rule framework is: set goals, understand risk, diversify, control costs, match investments to your time horizon, manage emotions, and research investments before buying.
There is no single official US “seven rules” standard.
Can I double my money in 5 years?
It is possible, but not guaranteed. Doubling money in five years requires approximately a 14.87% annual compounded return, before taxes and fees.
Higher return targets generally involve greater risk.
Is an investor awareness program free?
It depends on the organization. Some investor education resources are available free of charge, while private seminars or financial education programs may charge fees.
Always check whether a program is educational or connected to product sales.
Does investor education eliminate investment risk?
No. Education can help investors understand and manage risk, but it cannot eliminate market losses or guarantee investment performance.
Every investment decision involves some level of uncertainty.
Are investments bought through a bank FDIC-insured?
Not necessarily. FDIC insurance covers qualifying deposit accounts, but it does not cover stocks, bonds, mutual funds, crypto assets, and other non-deposit investments.
Check the specific product before assuming your money is insured.
Conclusion
Understanding an investor awareness program is really about grasping the purpose of investor education: helping people make informed decisions with their own money.
Investors should also know the difference between bank deposits and investments. FDIC deposit insurance covers qualifying deposit accounts at FDIC-insured banks, but other products, such as stocks, bonds, mutual funds, and crypto assets, are not FDIC-insured.
For anyone investing in the United States, the basic rules are simple: set clear objectives, understand what you are acquiring, diversify correctly, check costs, avoid emotionally based decisions, and beware of offers that seem too good to be true.
Most importantly, investor awareness does not guarantee profits. Its real value is giving people the knowledge to ask better questions and make financial decisions with greater confidence and care.
Pingback: SpaceX Stock Price 2030 Forecast: How High Could SPCX Go?