See what you have left each month and understand how your spending measures up against the 50/30/20 budgeting guideline.
50/30/20 Budget Calculator
Build a simple monthly budget from your take income. See how much to spend on needs, wants, and savings using the 50/30/20 budgeting guideline.
Start with your take-home income
Enter the money you actually receive after taxes and deductions.
Your 50/30/20 Budget
Recommended monthly allocation based on your take-home income.
Add your actual monthly expenses
Optional: enter what you normally spend to compare your real budget with the 50/30/20 targets.
Needs
50% targetWants
30% targetSavings & Debt
20% targetYour Budget Summary
See how much of your monthly income is currently assigned.
Your Recommended Budget Split
The standard guideline divides your take-home income into three categories.
Target vs. Your Budget
Compare the recommended amount with the expenses you entered.
| Category | Target | Your Budget | Difference |
|---|---|---|---|
| Needs | $0 | $0 | $0 |
| Wants | $0 | $0 | $0 |
| Savings & Debt | $0 | $0 | $0 |
Save Your Budget
Your calculations stay in your browser. Use the buttons below to save or share your results.
How this calculator works: The 50/30/20 budgeting guideline uses 50% of take-home income for needs, 30% for wants, and 20% for savings and extra debt payments. It is a general budgeting framework, not a requirement. Your ideal percentages may be different depending on your income, housing costs, debt, family situation, location, and financial goals.
This calculator is provided for educational and planning purposes only. It does not provide financial, investment, tax, or legal advice.
How to Use a 50/30/20 Budget Calculator
A budget can help you understand where your money goes each month and whether your spending matches your financial priorities. The 50/30/20 budget rule is one simple way to organize your money without having to create a complicated spending plan.
This calculator helps you apply that rule to your own finances. Enter your monthly income and expenses to see how much you are spending on needs, wants, savings and debt. You can then compare your numbers with the 50/30/20 guideline and see how much money you may have left over.
What Is the 50/30/20 Budget Rule?
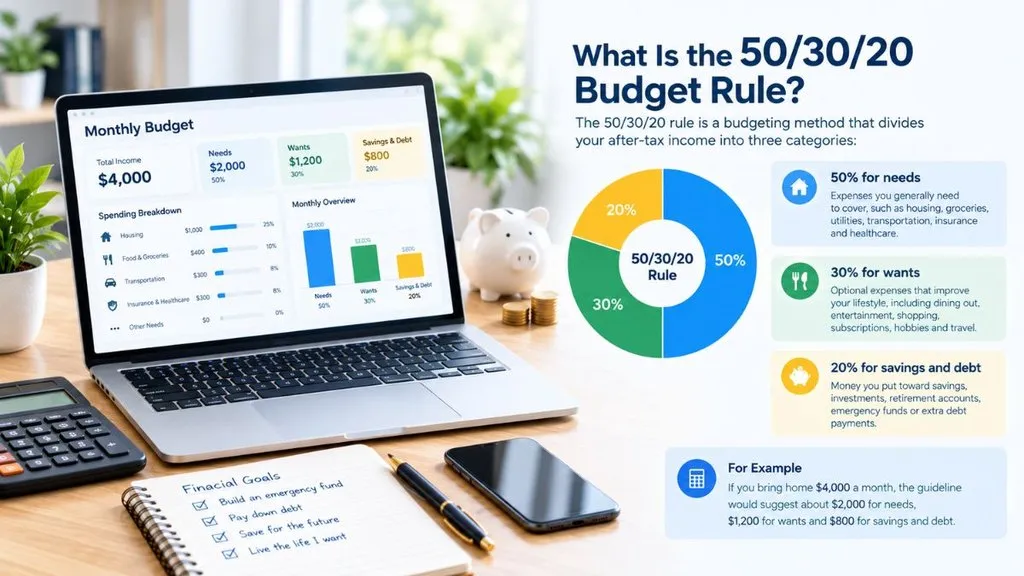
The 50/30/20 rule is a budgeting method that divides your after-tax income into three categories:
- 50% for needs: Expenses you generally need to cover, such as housing, groceries, utilities, transportation, insurance and healthcare.
- 30% for wants: Optional expenses that improve your lifestyle, including dining out, entertainment, shopping, subscriptions, hobbies and travel.
- 20% for savings and debt: Money you put toward savings, investments, retirement accounts, emergency funds or extra debt payments.
For example, if you bring home $4,000 a month, the guideline would suggest about $2,000 for needs, $1,200 for wants and $800 for savings and debt.
These percentages are not strict requirements. Your ideal budget may look different depending on your income, cost of living, family situation and financial goals.
Start With Your Monthly Income
The first step is to enter the amount of money you actually receive after taxes and other payroll deductions. This is sometimes called your take-home pay or net income.
If your income changes from month to month, such as when you’re self-employed or working on commission, consider using an average monthly income based on several recent months. Using a realistic number can give you a more useful estimate.
Add Your Essential Expenses
Next, enter the expenses you need to pay each month. These are your basic living costs and typically include rent or mortgage payments, electricity, water, groceries, transportation, insurance, healthcare and minimum debt payments.
Try to use your typical monthly spending rather than an unusually high or low month. If a bill is paid annually or irregularly, you can estimate its monthly equivalent by dividing the yearly amount by 12.
For example, a $1,200 annual insurance bill works out to about $100 per month.
Add Your Wants
Wants are expenses you could potentially reduce or live without. Common examples include restaurants, streaming services, entertainment, vacations, hobbies, shopping and other discretionary purchases.
This category can be useful because these expenses are often easier to adjust when you need to free up money.
That doesn’t mean you have to eliminate them. A realistic budget should leave room for enjoyment while keeping your overall spending under control.
Include Savings and Debt Payments
The final part of the calculator looks at money going toward your financial future.
This can include contributions to an emergency fund, retirement savings, investments and additional payments toward credit cards, personal loans or other debt.
If you’re currently saving less than 20%, don’t assume you’ve failed at budgeting. The 20% target is simply a guideline. Even a small, consistent contribution can help you build better financial habits.
What Does Your Result Mean?
Once you’ve entered your information, look at how your actual spending compares with the suggested percentages.
If your needs are well above 50%, you may have limited flexibility in your budget. If wants are taking up more than 30%, you may be able to find opportunities to reduce discretionary spending. You’re putting 20% or more toward savings and debt, you’re directing a meaningful portion of your income toward future financial goals.
The calculator may also show money left over after your listed expenses. That amount can give you an idea of how much additional room you have in your monthly budget.
Remember: 50/30/20 Is a Guideline
Your results don’t need to match 50/30/20 perfectly. Someone living in a high-cost area may spend more than 50% on necessities, while someone with a lower cost of living may be able to save considerably more than 20%.
Use the calculator as a starting point, not a pass-or-fail test. The most useful budget is one that reflects your real life and helps you make informed decisions.
Review your numbers regularly as your income, bills and financial goals change. Even small adjustments can make it easier to spend intentionally, build savings and stay on track with your money.
Pingback: Wall Street Analysts Say Oracle’s Earnings Checked Nearly Every Box