Wall Street analysts reacted positively to Oracle’s latest earnings report, with several saying the results addressed many of the concerns that had weighed on the technology company’s stock. Strong cloud growth, rising artificial intelligence demand and a much larger backlog helped shift attention toward Oracle’s long-term growth prospects.
Oracle’s fiscal first-quarter results exceeded analysts’ expectations, although investors remain focused on the company’s enormous spending requirements and its ability to turn AI demand into sustainable cash flow.
Oracle Earnings Beat Expectations
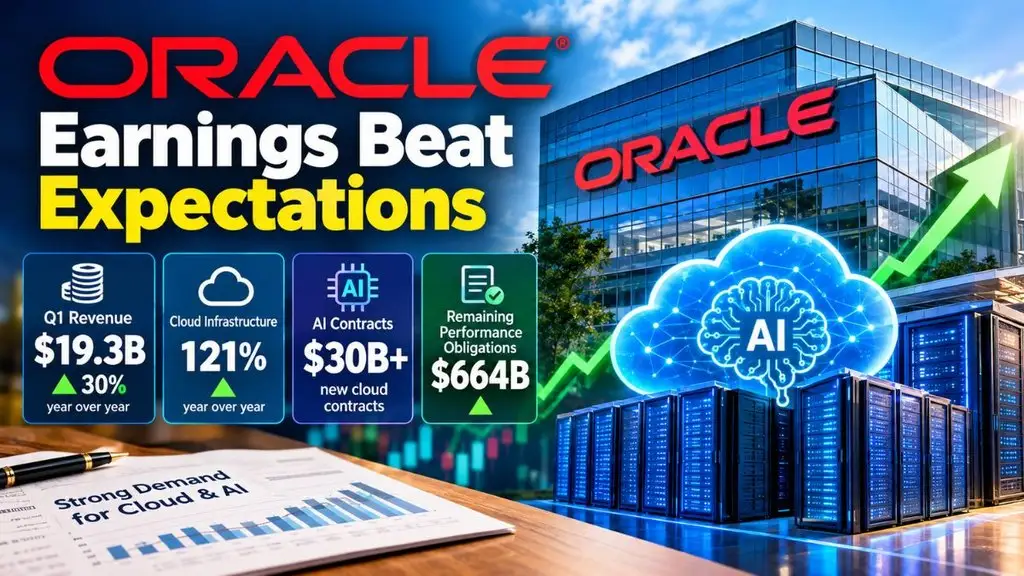
Oracle reported first-quarter revenue of approximately $19.3 billion, up 30% from a year earlier. Adjusted earnings came in at $1.92 per share, above the roughly $1.74 expected by analysts.
The company’s cloud operations were particularly important. Oracle Cloud Infrastructure revenue increased 121% year over year, highlighting the growing demand for computing capacity linked to artificial intelligence and other cloud workloads.
The results also included more than $30 billion in new AI-related cloud contracts. Oracle’s remaining performance obligations, a measure of contracted future revenue, climbed to about $664 billion.
These figures gave analysts more evidence that Oracle’s large investments in data centers are beginning to translate into customer demand.
Why Analysts Were Encouraged
Citi was among the firms taking a particularly positive view of the results. The firm maintained its Buy rating and described the earnings report as having checked nearly every box.
JPMorgan analysts also pointed to the strength of Oracle’s cloud business as a reason for greater confidence in the company’s strategy.
However, not every analyst became bullish. Morgan Stanley remained more cautious, maintaining a Neutral rating and emphasizing the need for additional evidence that Oracle can manage margins while expanding its cloud capacity.
That difference is important because Oracle’s growth story comes with unusually high infrastructure costs.
For readers who want to better understand how to organize their own finances alongside following market developments, the 50/30/20 budget calculator can help divide income between needs, wants, and savings in a simple way.
Oracle’s AI Spending Remains a Key Concern
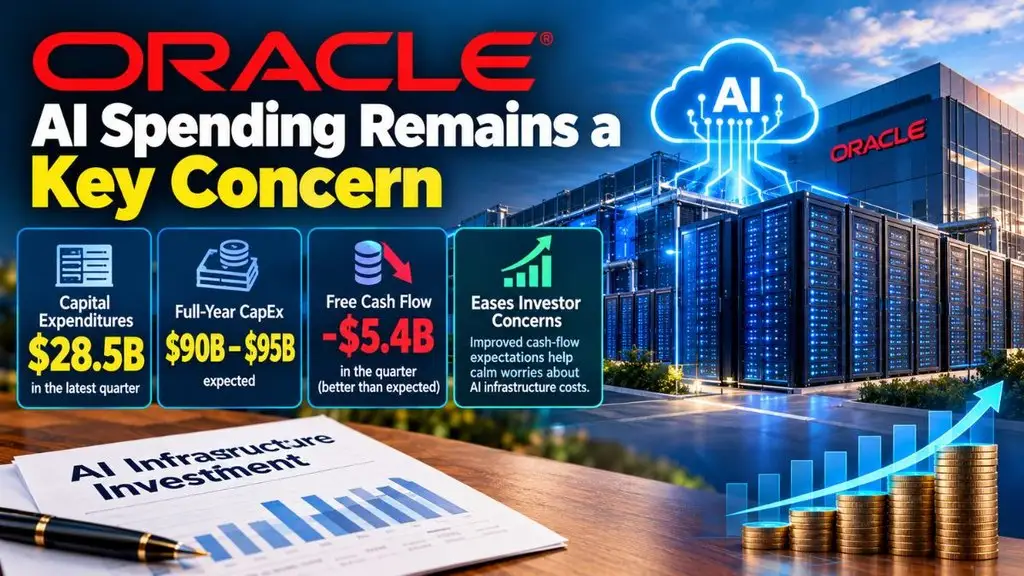
Oracle is spending heavily to expand data-center capacity for AI customers. Capital expenditures reached about $28.5 billion in the latest quarter, while the company expects full-year capital spending of roughly $90 billion to $95 billion.
Such spending can support faster growth, but it also places pressure on cash flow. Oracle reported negative free cash flow of about $5.4 billion for the quarter, although that was substantially better than analysts had expected.
The improvement in cash-flow expectations helped ease some investor concerns surrounding the scale of Oracle’s AI infrastructure spending.
Oracle Raises Its Fiscal 2027 Outlook
Another significant development was Oracle’s updated outlook.
The company raised its fiscal 2027 adjusted earnings forecast to at least $8.10 per share and maintained its expectation for at least $90 billion in revenue. For the upcoming fiscal second quarter, Oracle expects revenue growth of approximately 30% to 34%.
The guidance suggests management expects demand for cloud infrastructure and AI services to remain strong.
What Wall Street Will Watch Next
Oracle’s next earnings report will provide an important test of whether the company can maintain the momentum highlighted in its latest results. Analysts are likely to focus on cloud infrastructure growth, new AI contracts, capital spending and free cash flow.
The pace of data-center expansion will also remain important because Oracle is committing substantial resources to meet customer demand. Investors will want to see whether higher revenue can eventually offset the costs of expanding capacity.
If cloud growth remains strong while cash flow improves, confidence in Oracle’s strategy could increase. At the same time, slower growth or rising costs could renew concerns about the company’s AI investment strategy.
What It Means for Oracle Investors
The latest earnings report does not eliminate the risks surrounding Oracle. The company still faces questions about capital spending, margins, data-center expansion and its reliance on major AI customers.
Nevertheless, the results provide a stronger argument that Oracle’s aggressive infrastructure strategy is generating substantial demand.
Wall Street’s reaction therefore reflects two competing ideas: Oracle is demonstrating powerful AI and cloud growth, but investors still need to see whether that growth can produce attractive financial returns after the enormous cost of building the necessary infrastructure.
For now, analysts appear more confident in Oracle’s growth trajectory than they were before the earnings report. The next major test will be whether Oracle can maintain its cloud momentum while improving cash generation and managing the costs associated with its AI expansion.
Pingback: Intel and SK Hynix Stocks: Why Investors Are Watching the Chipmakers