A financial plan sample can help you understand how different parts of your financial life work together. Instead of focusing only on your monthly budget or investment account, a complete financial plan looks at your income, expenses, savings, debt, investments, protection, and future goals.
You do not need a complicated spreadsheet or a large investment portfolio to create one. A simple financial plan can start with three things: understanding where you are financially, deciding where you want to go, and creating practical steps to get there.
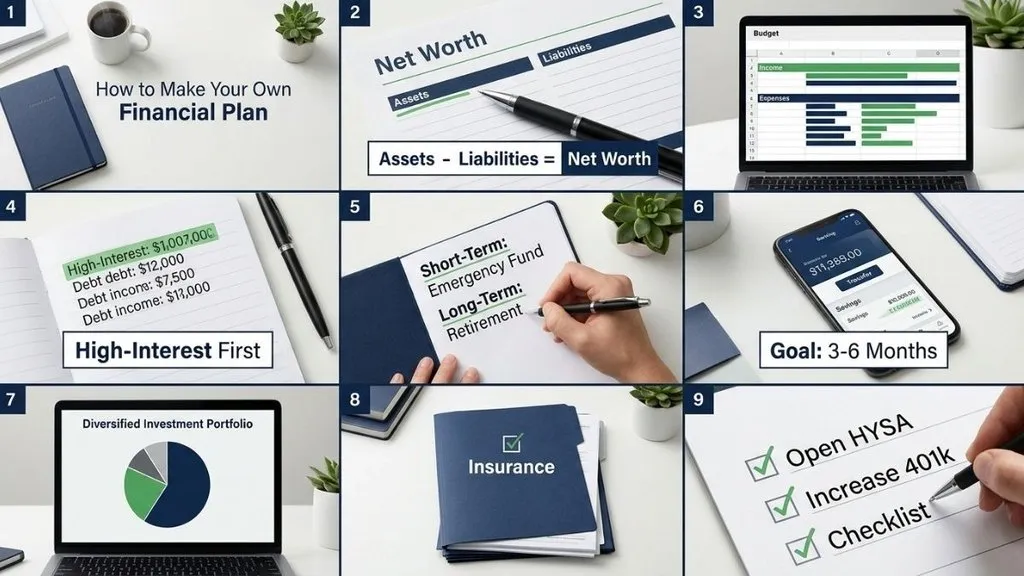
What Is a Financial Plan?
A financial plan is a written roadmap that helps you manage your money and work toward specific financial goals. It brings together decisions about spending, saving, debt, investing, risk management, and future financial needs.
Think of it as a guide rather than a prediction. Your income, expenses, family situation, taxes, and goals can change over time. When they do, your financial plan should be updated as well.
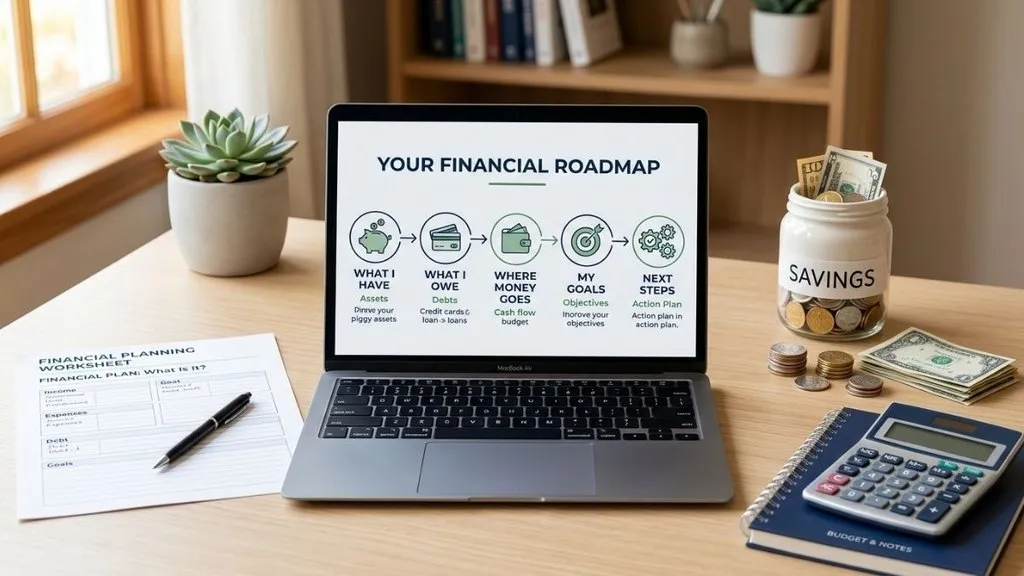
At its simplest, a financial plan should answer five questions:
- What do I have?
- What do I owe?
- Where is my money going?
- What am I trying to achieve?
- What should I do next?
Having clear answers to these questions gives you a better starting point for making financial decisions. You can learn about Social Security COLA 2027 to understand the latest COLA projections, how the adjustment is calculated, and what it could mean for Social Security benefits.
What Should a Financial Plan Include?
A complete financial plan can cover many areas. Still, most personal plans can be organized around a few key areas: financial goals, cash flow, savings and debt, investments, retirement, and financial protection.
1. Financial Goals
Start with your goals rather than your investments. Think about what you want your money to accomplish.
Your goals might include building an emergency fund, paying off debt, buying a home, paying for education, starting a business, or preparing for retirement.
Try to make each goal specific. Saying “I want to save more” gives you little direction. A goal such as “I want to save $6,000 for an emergency fund within 12 months” is much easier to measure and work toward.
A specific goal also helps you decide how much money you need to set aside and when you need it.
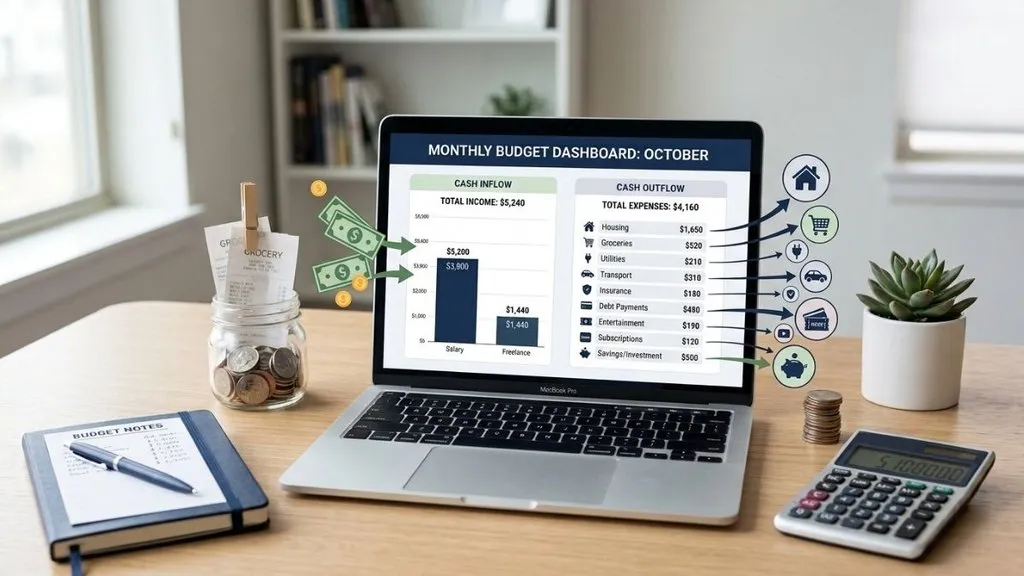
2. Cash Flow and Budgeting
Cash flow is simply the money coming into and leaving your household.
Start by recording your regular income and monthly expenses. Include essential costs such as housing, food, utilities, transportation, insurance, and debt payments. Then consider discretionary spending such as entertainment, subscriptions, hobbies, and dining out.
This process can show you where your money is actually going.
Remember that a budget is only one part of a financial plan. A budget tells you how you are spending your money today, while a financial plan also considers what you should do with the money left over and how those decisions support your future goals.
3. Savings and Debt
Your financial plan should show how much you have saved and how much you owe.
List your savings accounts, emergency funds, and other cash reserves. Then list your debts, including the outstanding balance, interest rate, and minimum payment.
Having this information in one place makes it easier to set priorities.
For example, if you have high-interest credit-card debt, paying it down may be an important priority before putting additional money toward certain long-term goals. The right approach depends on your overall financial situation.
4. Investments and Retirement
Your investments should have a purpose. Rather than choosing investments first, consider what each investment is supposed to help you accomplish.
Important factors include your financial goal, investment time horizon, and risk tolerance. Risk tolerance refers to how much investment loss you can reasonably handle financially and emotionally.
Retirement planning may include your current retirement savings, regular contributions, employer contributions where available, estimated retirement expenses, and possible sources of retirement income.
Investment returns are never guaranteed. Any future projections should be treated as estimates rather than promises. Investments should be connected to specific goals. Before choosing an investment, consider how long you have before you need the money and how much risk you can handle. Understanding investment risk can help you make more informed decisions.
5. Insurance, Taxes, and Estate Planning
A financial plan should also consider what could go wrong and how you would deal with those risks.
Depending on your circumstances, this may include health, life, disability, property, and liability insurance.
Taxes can also affect how much of your income and investment gains you actually keep. Estate planning focuses on what happens to your assets if you die or become unable to make important financial decisions.
You may not need an elaborate plan in every area, but ignoring these issues completely can leave important gaps in your financial strategy.
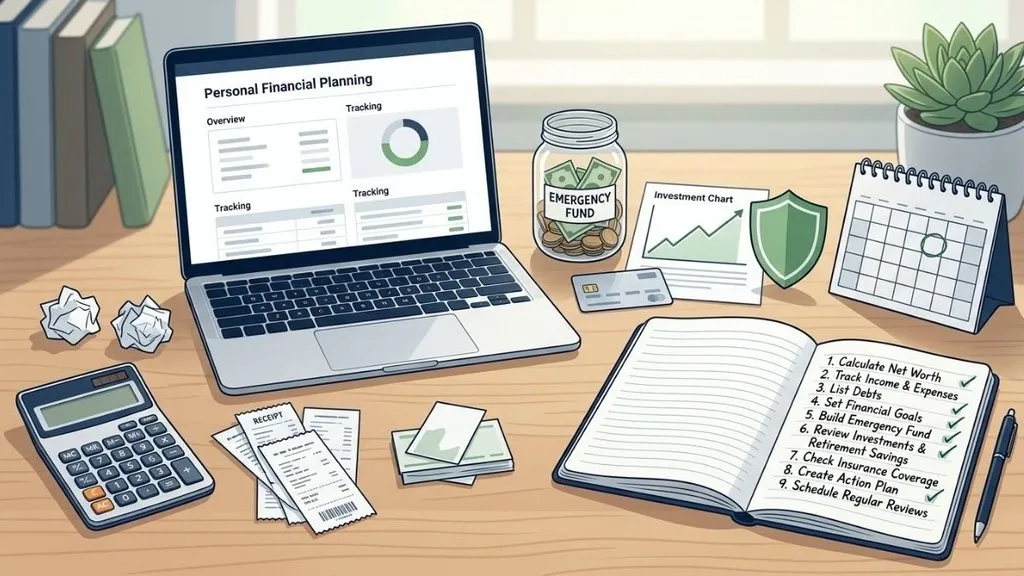
A Simple Financial Plan Example
Consider this hypothetical example.
Sarah is 30 years old and earns $60,000 per year. She currently has $8,000 in savings and $4,000 in credit-card debt. Her main goals are to buy a home within five years and continue building retirement savings.
Her financial plan could look like this:
Current financial position:
$8,000 in savings, $4,000 in credit-card debt, and $60,000 in annual income.
Short-term priority:
Build an emergency reserve while making steady progress toward paying off high-interest debt.
Five-year goal:
Save money toward a potential home down payment.
Long-term goal:
Make regular retirement contributions and increase them when her income and budget allow.
Investment approach:
Keep money needed for a home purchase within a relatively short timeframe separate from money intended for long-term retirement investing.
Action plan:
Review monthly spending, automate savings, reduce expensive debt, and review retirement contributions regularly.
This example is only for illustration. There is no single financial plan that works for everyone. Your income, expenses, debt, taxes, family situation, location, risk tolerance, and personal goals all affect the decisions that make sense for you.
What Are the 5 Components of a Financial Plan?
There is no single universal formula for the five components of a financial plan. However, a useful framework includes financial goals, budgeting and cash flow, savings and debt, investments and retirement, and risk protection.
Your financial goals explain what you want to accomplish. Your budget and cash flow show how much money is available to work toward those goals.
Savings and debt help establish financial stability. Investments and retirement planning focus on longer-term needs, while risk protection considers insurance and other issues that could affect your financial security.
Different financial planners may organize these areas differently, but the basic idea remains the same: a complete financial plan should look at your financial life as a whole.
What Is the 50/30/20 Rule in a Financial Plan?
The 50/30/20 Rule is a simple budgeting framework that divides your after-tax income into three broad categories:
- 50% for needs
- 30% for wants
- 20% for savings and debt repayment
For example, if your monthly take-home income is $4,000, the framework would suggest approximately:
- $2,000 for needs
- $1,200 for wants
- $800 for savings or debt repayment
These percentages are not requirements. They are simply a starting point for organizing your money.
Someone living in an expensive area may spend more than 50% of their income on essential costs. A person aggressively paying down debt may choose to put more than 20% toward debt repayment. Someone with a high income and low expenses may be able to save considerably more.
The most useful lesson is to give your income a purpose rather than spending first and saving only what remains.
How Do I Make My Own Financial Plan?
Making your own financial plan does not have to be complicated. Start by gathering accurate information about your current financial situation.
First, calculate your net worth. Add your assets, such as cash, savings, investments, and property, then subtract your debts and other liabilities.
Next, track your income and expenses. Try to use actual numbers rather than estimates.
Then create short-, medium-, and long-term goals. Give each goal a target amount and timeframe whenever possible.
After that, decide how much you can realistically save each month. Review your debt, emergency savings, insurance, investments, and retirement contributions.
Finally, turn everything into a short action plan.
A simple process could be:
- Calculate your net worth.
- Track your monthly income and expenses.
- List your debts and interest rates.
- Set financial goals.
- Decide on an emergency-fund target.
- Review your retirement and investment contributions.
- Review your insurance and other financial risks.
- Prioritize your next financial actions.
- Review the plan regularly.
A simple financial plan you actually follow is far more useful than a complicated one you never update.
What Is the 4-3-2-1 Rule in Finance?
The 4-3-2-1 Rule is a budgeting guideline that some financial education resources use to allocate income across different spending and saving categories. However, there is no single universally accepted version of this Rule, so the percentages and categories can vary.
One version allocates approximately 40% to needs, 30% to living expenses or bills, 20% to savings or investing, and 10% to discretionary or social spending.
Because different sources may explain the Rule differently, it should not be treated as a universal financial standard.
The more important idea is to intentionally divide your income. Your personal allocation should reflect your income, living costs, debt, savings needs, and financial goals.
Budgeting rules can give you a starting point, but your actual financial plan should be based on your circumstances.
How a Financial Planning Template Can Help
A financial planning template can make it easier to organize your financial information and identify what needs attention.
You can create a basic template in a spreadsheet, notebook, or financial-planning app. You do not need expensive software to get started.
For example:
Financial Area Current Position Goal Next Action
Emergency fund $2,000 $6,000 Automate monthly savings
Credit-card debt $4,000 $0 Increase repayment
Retirement $15,000 Grow consistently Review contributions
Home savings $5,000 $30,000 Save in a separate account
Insurance Existing coverage Appropriate protection Review annually
The figures in this table are hypothetical.
The important part is the structure. You can see where you currently stand, what you want to achieve, and the next action that can move you closer to the goal.
As your financial situation becomes more complicated, you can add information such as deadlines, monthly contributions, interest rates, account balances, and expected expenses.
Common Financial Planning Mistakes to Avoid
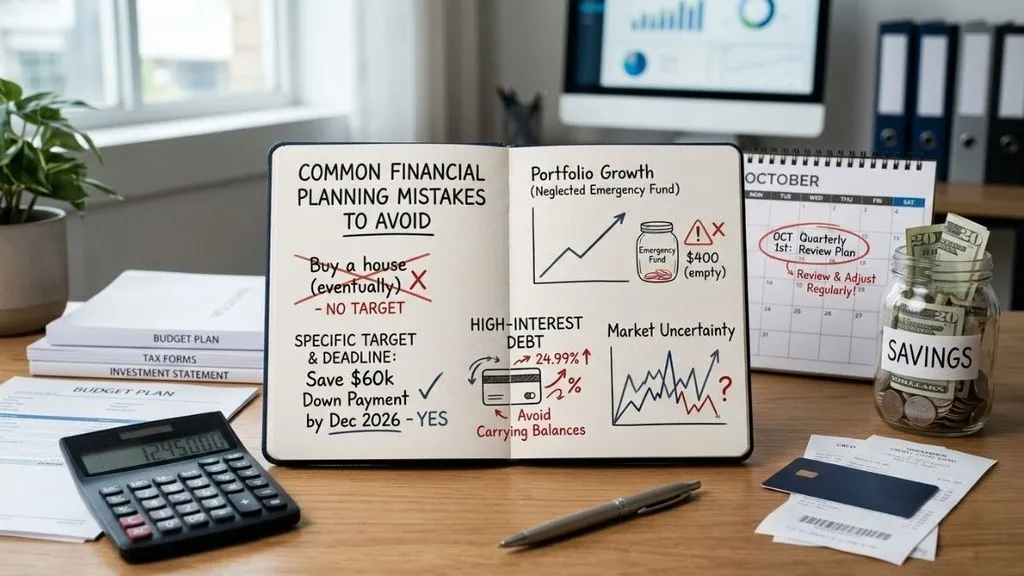
One of the most common mistakes is creating goals that are too vague. A goal such as “I want to become financially secure” does not tell you what to do. A goal with a specific amount and deadline is much easier to act on.
Another mistake is focusing too heavily on investments. Investments can be an important part of a long-term financial plan, but they do not replace emergency savings, debt management, insurance, or sensible spending.
Ignoring high-interest debt can also make financial progress more difficult. Interest can accumulate quickly, reducing the amount of money available for other goals.
It is also important not to treat financial projections as guarantees. Markets can rise or fall, inflation can change, income can increase or decrease, and unexpected expenses can appear.
Finally, do not create a financial plan once and then forget about it. Your financial situation changes throughout your life, so your plan should be reviewed and adjusted when necessary.
How Often Should You Review a Financial Plan?
For many people, reviewing a financial plan at least once a year is a reasonable starting point. You should also review it whenever you experience a major change in your financial or personal life.
For example, changing jobs, getting married, having a child, buying a home, starting a business, receiving an inheritance, or approaching retirement could all affect your financial priorities.
A review does not mean you need to change everything. Sometimes the best outcome is simply confirming that your existing plan still fits your circumstances.
The purpose of reviewing your financial plan is to make sure your goals, spending, savings, debt, investments, and financial protection continue to work together.
A financial plan cannot predict everything that will happen in the future. What it can do is give you a clearer framework for making financial decisions today.
FAQ’s
Is a financial plan the same as a budget?
No. A budget mainly focuses on income and spending, while a financial plan takes a broader view. It can include budgeting, saving, debt management, investing, insurance, retirement planning, taxes, and long-term financial goals.
Can I create a financial plan without a financial advisor?
Yes. You can create a basic personal financial plan using your financial statements, a spreadsheet, and clearly defined goals. More complicated situations involving taxes, estate planning, business ownership, or complex investments may require professional guidance.
Should I invest before paying off debt?
It depends on the type of debt, its interest rate, your financial goals, and your overall circumstances. High-interest debt may deserve significant attention, while certain employer retirement benefits may also influence how you divide your money.
How much should I keep in an emergency fund?
There is no single amount that is right for everyone. Consider your essential monthly expenses, income stability, dependents, insurance coverage, and how quickly you could replace your income if circumstances changed.
Can a financial plan guarantee that I will reach my goals?
No. A financial plan can help you organize your money and make more informed decisions, but it cannot guarantee investment returns, future income, market conditions, or expenses. Good planning involves realistic assumptions and regular adjustments.
Conclusion
Creating a financial plan does not have to be complicated. A simple plan can help you understand your current financial position, set realistic goals, manage spending, reduce debt, build savings, and prepare for the future. The most important step is to start with clear information and practical goals that match your situation. Use a financial plan sample or template as a starting point, then adjust it as your income, priorities, and circumstances change. Remember that a financial plan is a guide, not a guarantee. Review it regularly, make adjustments when needed, and focus on steady progress rather than trying to make every financial decision perfectly.
Pingback: High-Yield Savings Account Rates Today: What Savers Need to Know - finexaia.com